“If you suspected they were never really separate, you were right.”
More from LukeBrand is demand in B2B.
Why the real decision in B2B happens long before a vendor’s contacted, and what that means for where marketing budgets should go.

Introduction.
There’s an uncomfortable mismatch at the heart of how B2B marketing budgets are typically constructed, one that doesn’t hold up well under scrutiny. A common assumption is that activating paid media against the right audience and the right pain point will be enough to generate meaningful demand. LinkedIn campaigns, Google Ads, outreach sequences: these are the tactics that absorb the bulk of most marketing budgets, and they’re treated as demand generation almost by definition.
What this misses is that by the time the vast majority of buyers are ready to make contact with a vendor, the decision about who they want to work with has already been made. The real influence happened earlier, at a stage the majority of budgets simply weren’t present for.
Which raises a question worth sitting with: is there a fundamental misunderstanding, across the industry, about where the conversion point in a B2B purchase actually lies?
Strategy plans long. Activation acts short.
As an industry, we plan for the whole customer journey. Strategies account for the full arc of a B2B buying cycle, including the extended brand-building activity that notoriously long sales cycles require. When it comes to activation, though, those longer-term elements are often quietly shelved in favour of bottom-of-funnel tactics that are quicker, cheaper, and easier to evidence in reporting.
What the data consistently shows, however, is just how far upstream the critical decisions are taken. Two figures illustrate this.
94%
of eventual winners were already on the buyer's Day-1 shortlist when the buying group first formed.
85%
of winning vendors had prior relationships or existing engagements with the buying organisation before the active buying cycle
What this means in practice is, in the vast majority of cases, the winner has already been chosen before any contact is made with vendors. If a buyer only comes across your paid media campaign while they’re in the latter stages of the journey, you’re effectively trying to reverse a decision that’s already been made.
This raises a more fundamental question about where conversion in B2B actually takes place. It also shines a light on how much budget is spent on trying to affect decisions that have already been made and won’t be reversed.
The 95/5 rule.
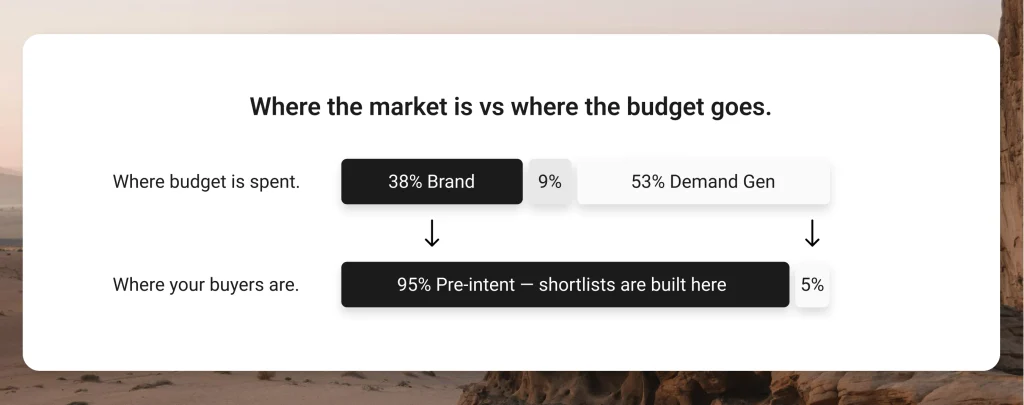
Almost all marketers can tell you the 95/5 rule, which states: “At any given moment, only 5% of your addressable market is actively buying. 95% are in a different part of the cycle.”
What the 95% are doing, throughout that extended period, is forming opinions, reading content, hearing names, and developing a sense of which companies seem to understand their world. This is where those all important Day-1 shortlists are actually built, often months or even years before a purchase initiative formally begins (6sense, 2025).
The problem is that budget allocation tells a very different story. Vendors spend 53% of discretionary budget on demand generation and just 38% on brand (TrustRadius, 2025), and among individual marketers, 49% rank lead generation as their top priority for 2026, while brand awareness is cited by just 21% (CoSchedule, 2026).
It is entirely rational for teams to prioritise what produces a visible result, especially when reporting cycles are 30 days and buying cycles are now averaging 272 days (Dreamdata, 2026). Brand investment is much harder to defend in a monthly pipeline review, and the incentive structures most marketing functions operate within make short-cycle thinking the path of least resistance. Most people in the room already know this. What the data suggests is that the cumulative effect of those rational individual decisions is quietly undermining commercial outcomes across the industry.
“You wouldn’t ask someone to marry you on the first date, and you shouldn’t ask a cold audience to book a demo on the first ad impression either. Over those 272 days, your job is to build familiarity, earn trust, and stay top of mind so that when that once-a-year buying window opens, you’re already the company they want to talk to.”
Dreamdata / LinkedIn Ads Benchmarks Report, 2026
This is not a marketing problem in itself. B2C brands have long understood that purchase decisions are driven as much by emotional connection as by rational evaluation, and have invested in brand accordingly. B2B has been slower to adopt the same approach, partly because there is an assumption that the buying process is more rational, and partly because the payoff horizon is long enough to be difficult to defend in a quarterly conversation.
The Day-1 shortlist is the real conversion event.
When we talk about Demand Generation, it’s often framed as a mechanism for creating commercial opportunities, with conversion happening somewhere downstream (a form fill, a discovery call, an RFP response). But if most winners have already been decided way before that stage in the journey, hasn’t the conversion already happened?
The argument is simple: brand authority gets you onto the Day-1 shortlist – and that’s where your opportunities come from. Everything else lower down the funnel is just closing the deal. The numbers make this difficult to ignore.
68%
of vendors ranked first at the selection stage win the deal in UK and Ireland. Being fourth on a shortlist is, in practise, expensive demo practice.
79%
of all buyers, and 89% of enterprise buyers, already knew the product they eventually purchased before their formal research even began.
61%
of buyers enter the formal process with a preferred vendor already in mind, and 16% say the decision is already effectively made before any vendor contact.
The pattern is consistent across every data set. Buyers are not discovering vendors and then deciding. They arrive at the formal process with preferences already formed, shortlists already set, and in many cases a preferred vendor already identified. The active buying cycle, the part that CRMs capture and sales teams report on, is largely a confirmation exercise rather than a truly open competition.
For UK and Ireland buyers specifically, the first 57% of the journey, roughly 4.5 months in an 8-month cycle, happens entirely without vendor contact (6sense, 2025). Buying groups are forming, requirements are being written, and shortlists are being created and ranked, all before a brand knows the opportunity exists. A brand that is not already known during this phase is simply not being considered for the list that will determine who wins the deal.
Mid-funnel and late-funnel tactics are still important, but the reality is that they should be understood as closing tactics rather than demand generation. The demand was created, or lost, long before they were deployed.
Why brand authority is key to getting on that shortlist.
Before getting into this, it is worth saying clearly: there is no single prescription here. For some businesses, brand authority is built at industry events and conferences. For others, it comes through the publications their buyers read, a podcast, or a consistent presence in the communities where their peers share ideas. What holds true regardless of the channel is the quality and relevance of what you put out into the market.
A crucial part of building brand authority is your content strategy. Before anything else, it needs to answer one question:
Does this give our audience something they will actually find useful?
Content that keeps a brand top of mind across that long pre-intent phase tends to do at least one of three things:
- Makes someone’s job meaningfully easier.
- Challenges how they think about a problem they already care about.
- Gives them something genuinely worth sharing with their peers.
This is always easier when you have done the foundational work: a defined brand voice, a clear market position, and a genuine understanding of where your product or service fits in your buyers’ world. Taken together, these give you something distinctive to say, and the clarity to say it consistently.
“It is possible to build brand authority just from an email newsletter, if it’s good enough. The point is you have to give people something that makes them stop and think ‘yes, this is worth my time.’ Everything else is just noise.”
Sam Hodgson, Head of Client Delivery, Invanity
Buyers are more receptive to this than is often assumed. Strong thought leadership really does influence the buying process, demonstrating niche expertise to an audience that is actively looking for it. It also reaches members of the buying committee who are hidden from view; the finance, legal, and procurement stakeholders who will never take a sales call but frequently shape the final decision.
71%
of hidden decision-makers say thought leadership is more effective than conventional marketing at demonstrating a supplier's value.
53%
of buyers agree that if the thought leadership is genuinely good, brand recognition matters less. Challengers can outcompete incumbents through ideas.
There is a discoverability dimension worth noting too. The authority signals that search algorithms and AI systems use to decide what to surface (such as clear expertise, credible sourcing, a consistent point of view) are unsurprisingly the same ones that earn trust from buyers in the first place. As AI-mediated discovery becomes a bigger part of how buyers research vendors, the brands that invest in genuine authority will increasingly be the ones that get cited, recommended, and found.
19% vs 12%
19% revenue growth for companies with a clearly differentiated value proposition, compared to 12% for those without one. Only 4% of global B2B executives say their organisation actually has one.
Of course, knowing that differentiation matters is one thing, having something that is actually different to say is quite another. This is where many brands stall, but also where the greatest opportunity sits. Closing that gap is less a creative challenge than a strategic one: it requires clarity about who you are, what you stand for, and what your audience needs to hear from you.
Bringing it together.
The data tells a consistent story. Commercial opportunity forms long before a buyer contacts a vendor, in the months and years when they are building opinions, consuming content, and quietly assembling their shortlists. By the time your paid campaigns find them, most of those decisions have already been made.
Getting on the Day-1 shortlist is the conversion event. Everything that follows is how you close what brand has already made possible, and the two deserve to be understood that way, as complementary parts of the same process rather than competing claims on the same budget.
The question for most marketing teams is not whether this is true. Most people in the room already suspect it is. The question is whether the way you plan, invest, and measure reflects it.